

Your AP Team Doesn't Need to Spot a Deepfake
AI is making fraud harder to recognize. But for most AP teams, the real risk doesn't arrive as an obvious deepfake or a suspicious AI-generated invoice. It arrives looking completely routine.
An invoice that looks like every other invoice. A payment request that sounds reasonable. A document with the right logo, the right formatting, a plausible PO number.
The question was never whether your team can tell what's real. It's whether your controls would catch a bad transaction before money moves.
For CFOs and AP leaders, that's the reality that matters: You cannot build a fraud strategy around employees being able to spot the fake. And increasingly, they shouldn't have to.
AI is making an existing AP problem harder
The FBI's 2025 Internet Crime Report recorded 22,364 AI-related complaints representing more than $893 million in reported losses.1 But there's an important caveat to that number.
The FBI categorizes "AI Related" as a descriptor associated with a reported crime. That designation depends on AI being identified in the information reported to IC3, meaning reported AI-related losses don't necessarily capture every fraud in which AI played a role.2
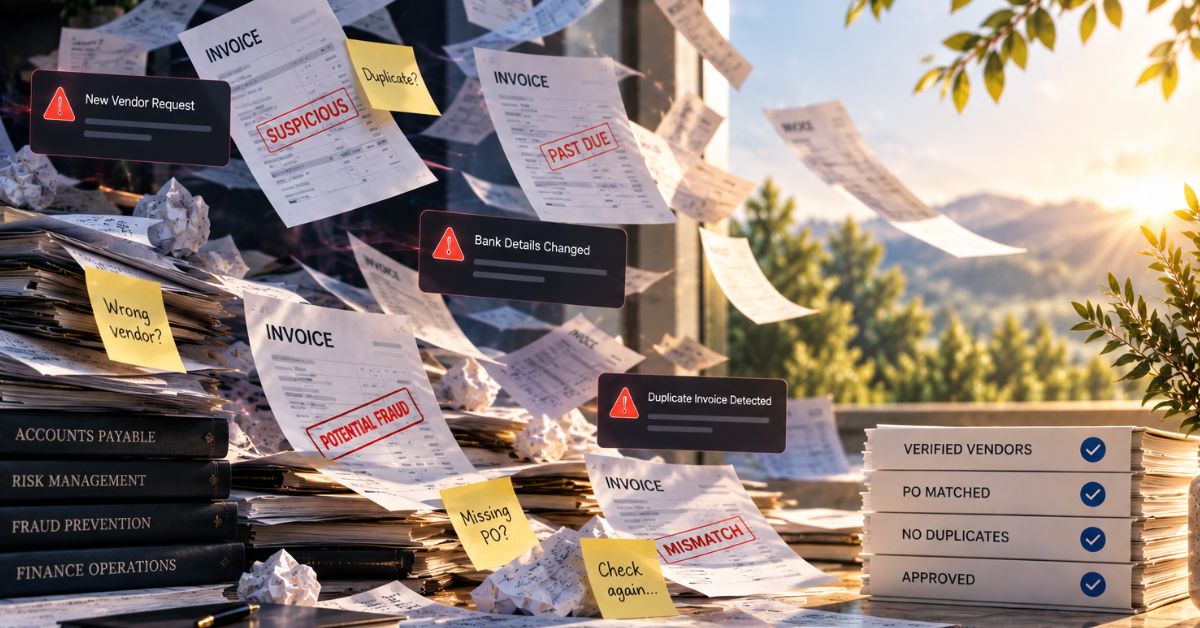
For AP teams, the bigger takeaway isn't the number. It's that AI makes the fraud scenarios finance teams already worry about more convincing. Business email compromise. Vendor impersonation. Fraudulent payment instructions. Duplicate invoices. Documents that look legitimate enough to move through a busy AP department.
That changes the question CFOs should be asking. Not: Can my team recognize an AI-generated fake? But: Would our AP controls stop the transaction even if nobody realized it was fake? Stop trying to identify the fake. Verify the transaction.
The strongest AP controls don't need to determine whether an invoice was created by a person or generated by AI. They check whether the transaction matches what your business already knows to be true. For AP teams, that comes down to three fundamental questions.
1. Do we actually know this vendor?
An AI-generated document can look flawless. What it can't do is fabricate a history inside your financial systems. Is this an approved vendor? Have we paid them before? Do the details match what we already have on file? That established history is a control in itself, one that appearance alone can't fake.
The same principle applies when something about a vendor is asked to change. A request to update payment details shouldn't be trusted because the email looks right. It should be verified against the information you already hold and routed through a controlled process, not confirmed using the contact details included in the request itself. AI can create a convincing request. It can't create a track record inside your systems.
2. Did this transaction actually happen?
This is where purchase order and receipt matching become even more important. A fraudulent invoice can look perfect. It can include the correct logo, realistic line items, convincing payment terms, even a plausible PO number. But does it match a purchase order someone actually created? Were the goods or services actually received? Do the quantities and amounts reconcile?
A fake invoice can look perfect. It still cannot match goods nobody received. Two-way, three-way, and four-way matching move the control away from judging the document itself and toward validating the underlying transaction, automatically, on every invoice, before anything posts.
3. Have we seen this before?
A fraudulent invoice doesn't necessarily look fraudulent. It may look almost exactly like something your AP team has processed hundreds of times before. That familiarity is what makes it easy to miss. That's why duplicate detection can't just mean matching two identical PDFs. It means checking each new invoice against the history of invoices already in the system: the vendor, the document type, the invoice number, and the document itself. An invoice may look new to the person reviewing it. Your AP history may tell a different story.
AI fraud is really a controls problem
The response to AI-powered fraud isn't simply layering more AI on top of existing processes. It's making sure the underlying financial controls are strong enough to work regardless of how convincing a document, email, or request appears.
For CFOs and AP leaders, that means asking a few fundamental questions:
- Is our vendor master governed, and are changes to it controlled?
- Are invoices consistently matched against POs and receipts?
- Are potential duplicates checked against the invoices we've already seen?
- Are exceptions surfaced and resolved before invoices move to payment?
Automation matters because these controls are only as effective as their consistency. Manual processes inevitably create gaps. Someone has to notice the change, remember the procedure, perform the check, or have enough time to investigate an exception. Automated AP applies those controls to every invoice, not just the ones someone had time to review.
Writing a control is different from running it every time
Most finance organizations know what good controls look like. The harder part is making them actually happen, on every invoice, across every entity, vendor, PO, receipt, approval, and exception. That's where the build-versus-buy question becomes real.
Keeping ERP master data in sync, maintaining matching logic, checking every incoming invoice against your full history, routing exceptions, and adapting as the business changes isn't a rule you write once or an RPA workflow you bolt on. It's infrastructure, and it has to run consistently, at scale, every day.
There's a meaningful difference between having a control documented and knowing it ran when it mattered. That difference is exactly what automation is for. The controls that hold up aren't the ones that depend on someone noticing a document "looks wrong." They're the ones that run on every invoice, every vendor, every transaction, consistently, whether AP reviewed it closely or not.
It's also why good data matters. Duplicate detection weakens when the same supplier exists under multiple records. Matching creates noise when purchasing and receipt data are inconsistent. Vendor controls break down when no one owns how a vendor record gets created or changed. AI doesn't remove the need for those fundamentals. It makes them more important, and automation is what lets you apply them at a scale manual review never could.
The goal isn't to turn AP teams into deepfake experts. The goal is to build an AP process where spotting the fake isn't necessary in the first place.
See how Vic.ai helps finance teams build more consistent, automated AP processes.
Read our CFO's Guide to AI Security and Trust